Musings
The things that move share prices
I have recently been reading through well-known investing blogs like Bronte Capital (John Hempton) and Bristlemouth (Forager/Steve Johnson) from their beginnings in 2008 or so. They are very good. I read Hempton’s in its entirety a few years ago and I would recommend his earlier posts as an excellent crash course in how the truck …
I have recently been reading through well-known investing blogs like Bronte Capital (John Hempton) and Bristlemouth (Forager/Steve Johnson) from their beginnings in 2008 or so. They are very good. I read Hempton’s in its entirety a few years ago and I would recommend his earlier posts as an excellent crash course in how the truck banking actually ‘works’ when the rubber hits the road (i.e., when the liabilities hit the shareholders).
If you know some other good Australian investing blogs, I’m compiling a list, so please leave suggestions in the comments.
In the course of reading both blogs I have come to an insight that I think is often overlooked in investing. Most professional investors make specific use of this piece of knowledge but I haven’t seen it mentioned explicitly.
I am not entirely sure what to call it (I am sure that there is a CFA term for it, if you know it feel free to jump in) but for the time being I will call it:
‘Factor-driven investing’
It’s fairly obvious. I think most investors use it implicitly but I’m finding that stating things explicitly in the blog is helping my process a lot. More relevantly, all of the 10foot companies so far are businesses that require, in one way or another, a re-rating of their value. I have been thinking about various aspects of re-rating at some length.
Anyway, so ‘factor-driven investing’ (please give me a better name) is where you’re looking at a factor in your investment, such as the value of a company. But that factor does not line up with the primary factor that is driving the value of the investment. I.e., the value of your investment is being driven by something other than what you think is driving it.
Say you’re looking at company XYZ, and it looks really cheap. But because of the structure of the debt or whatever, the earnings/growth of the company is not what’s driving this company’s value. Which is weird, because don’t earnings drive company value?
RNY Property Trust (ASX: RNY) is a perfect example. The company was in breach of its debt covenants, but it was marketing its properties for sale to see if they could pay off the debt. On the face of it, the properties were worth a lot more than the debt. In that situation, I think it very unlikely that a lender would put the screws to the company. If they foreclosed on the loan, the company goes into administration, then you have to appoint administrators, pay bulk fees, and sell the assets anyway (usually for a poor price) to figure out what they’re worth. Losses are almost always more severe in this situation. The lender might as well wait a few months and see if RNY can pull it off. That’s exactly what happened, although unfortunately RNY didn’t pull it off.
However, in that situation, the value of the properties is not the driving factor of the investment. The ‘thing’ that drives the investment in the near term is the breached debt, or more specifically the patience of the lender and the likelihood of them tipping the company into administration. More importantly, if the lender is not patient, you are setting yourself up for a fall regardless of what the properties are ‘worth’.
So if you’re looking at the value of the properties and going ‘wow this investment is really cheap, I should buy it’ your process is wrong. What you were actually doing with RNY was making two bets – one on the value of the properties, and another – more important – bet on the patience of your banker. Which is perverse, because who wants to invest based on the patience of their banker? This is something that had to be identified and addressed before investing otherwise you were exposed to significant risk.
RNY was fairly straightforward. Most investors look at debt and maturation dates and so on when they research a company. Still I think it is important for investors to identify the factors that are actually driving the valuation.
That’s probably blatantly self-evident. I find it useful to spell out these things specifically because once a theory is laid out, it can be manipulated. E.g. one can ask ‘in what circumstances is this theory wrong?‘ etc., but that’s a story for another day/possibly never.
A current example: NGE Capital
One thing I think I will do for future investment theses is try to prioritise the ‘factors’ that are driving a company’s value and their expected timeframe. For example with NGE Capital (ASX: NGE) which I just purchased, the primary driver of the company’s value is the way that people are pricing the LIC.
That is the most over-riding concern in the near term. One week early in August, NGE shares fell 8% and the gap between share price and NTA widened by close to 10% despite no announcements from its major holdings. In fact, NGE’s net tangible assets grew measurably, yet its share price went down:
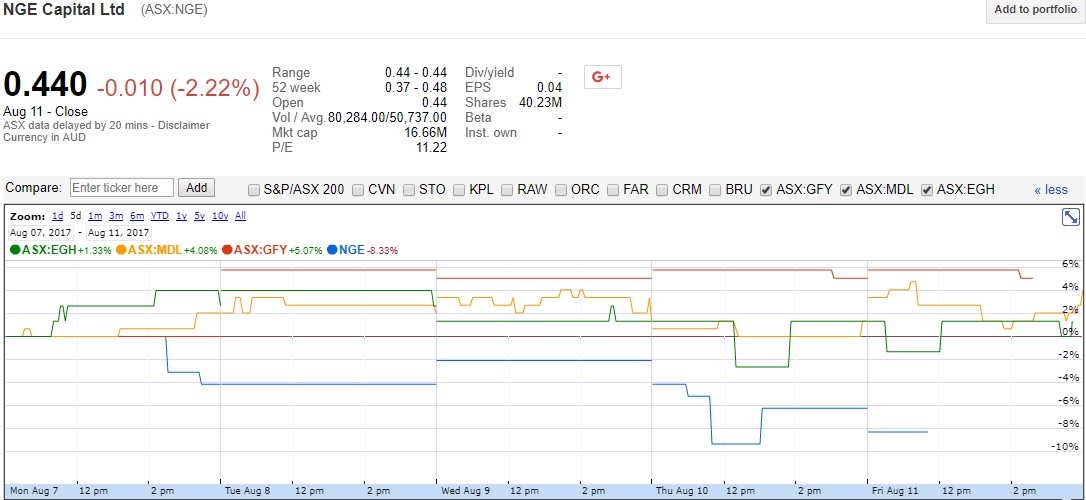
See NGE (blue line) vs the share price of its 3 largest positions (these account for 51% of NTA, plus NGE has 26% in cash) source: Google.
So the primary driver of my investment’s value is however the hell people decide to price NGE this week (the same can be said for every company). However, the second most ‘powerful’ factor, in terms of ability to influence LIC share price, but the most likely to cause lasting change (in my opinion), is the value of the underlying companies. I have come up with a preliminary list of factors in order of their ‘power’, which I define as ability and likelihood of influencing SP:
The 4 factors that have the biggest impact on NGE’s share price and their time frame
- The way that people price shares in the LIC (phases of the moon, motivation of buyers/sellers etc). Applies daily.
- The value of the underlying assets. Share price should generally track these quite well – approximately, and on average – over 6mth-1yr periods and longer.
- The success of the manager at making good investments. This is where you start talking about multiple ‘cycles’ of investments (selling winners/losers and searching for more purchases) and the presence or lack of a repeatable process. Applies over multi-year periods.
- The long-term reputation of the manager. This is like a ‘meta’ factor because it is semi-independent of a company’s assets. Forager LIC (ASX: FOR) is no more likely to outperform now than it was a year ago, but its units trade at a 20% premium to NTA – compared to previously when you could invest in the fund at a price equal to NAV. Arguably this is due to scarcity of units. If it’s the rep of the manager however, you’d expect the premium to NAV to remain fairly constant over the long term, just like with Wilson’s WAM Capital (ASX: WAM). Reputation influences share prices across the spectrum from daily to multi-year timeframes.
Over a 1-3-year time frame, the value of the underlying shares NGE holds should well and truly be the underpinning driver, especially since NGE is publicly traded and the manager appears to have a shorter-term timeframe (i.e., realises value more regularly). However, if for example, there’s no-one interested in buying or selling the LIC/ the manager doesn’t get a good rep/ doesn’t have a repeatable process etc, it will be difficult for NGE to re-rate. So there are a few different factors to keep an eye on.
In the future, hopefully I’ll find a situation where I can swing for the fences based on a factor mismatch that’s clearly in my favour. A further plunge in NGE’s share price, despite positive news flow at all its companies, might fall into that category.
I own shares in NGE Capital. I used to own shares in RNY Property Trust but recently sold the whole position. I have no financial interest in any of the other funds mentioned like Wilson, Forager, or Bronte. This is a disclosure and not a recommendation. You can follow 10foot on Twitter @10footinvestor.