Investing
Getswift and Amazon
Topical subject. Getswift Ltd (ASX: GSW) put out a barebones release announcing a deal with Amazon ($AMZN) on Friday morning, before being suspended by the ASX and instructed to prepare a more informative update – probably because shares were up over 100% at one point. The subsequent more informative update was emphatically not more informative, but I’ll get …
Topical subject. Getswift Ltd (ASX: GSW) put out a barebones release announcing a deal with Amazon ($AMZN) on Friday morning, before being suspended by the ASX and instructed to prepare a more informative update – probably because shares were up over 100% at one point. The subsequent more informative update was emphatically not more informative, but I’ll get to that.
The market is divided into two camps on Getswift. One camp thinks that VC missed the greatest investment since Facebook, and the other camp thinks that Getswift investors are going to get stiffed one way or another. It is a known fact that opposition only strengthens strong beliefs, so I do not see people revising their position in a hurry.
Some have suggested similarities between Getswift and 1-Page, a previously hot software company that also struck a much-touted deal with Amazon.
In the original version of this post I wrote that I thought that Aesir Capital may have also advised 1-Page. That was incorrect, it was Cygnet Capital that was involved with both Getswift and 1-Page, not Aesir. I apologise for the honest mistake.
So far it has been difficult to get a purchase on the Getswift business model as it works in practice. If Getswift gets anything like the number of transactions it is predicting, and at the prices it says it charges, then it will still do well from here. Now, there are a large number of yellow flags in my opinion including low R&D spend, director departures, low staff costs, limited tech support + sales staff infrastructure, and so on. Getswift is totally unsuitable for the 10foot portfolio because of these things.
If you don’t get the business model, how can you value Getswift?
Even putting those concerns aside, in my opinion, there are so many questions regarding these forecast transactions that I think Getswift watchers currently do not have any way of proving if the company is capable of doing what it says. Despite signing many deals, it is unarguable that the company has not yet demonstrated that deals lead to revenues. The next few quarters will be critical here I would think.
Additionally, with such limited disclosure – the company announces a huge-sounding deal with Amazon but doesn’t disclose the slightest information about it – mug punters like myself must resort to rampant speculation. And, since there are no details being released about the deals, in my opinion it is impossible to determine what they are worth with any accuracy. Which of course makes it very difficult to value Getswift.
I can’t tell you what the company is worth, because I don’t know. But to justify today’s market capitalisation, I think Getswift needs to hit $75m in revenue within the next 3 years, at high gross margins, and with further rapid growth still occurring. The company has a fully diluted market capitalisation of ~$765m including shares on issue, shares in escrow, in-the-money options (no OOTM options as far as I could see) and performance rights. $75m in revenue would price the company at ~10x sales, which is ‘fair’ for a software company with high margins (and strong customer retention and switching costs) that is growing rapidly. I’m not certain Getswift fits that criteria but I’ll get to that.
How do you determine the lifetime value of a Getswift deal?
Here are a few things I’ve been thinking about:
For example, is the contract ‘binding’ in any way? Are customers legally bound to use Getswift, are there switching costs, are there penalties if the customer chooses not to use Getswift? Is there anything to prevent clients shopping around for a better deal? Why don’t customers develop their own solution if they’re going to be spending $100m plus on deliveries? Can Getswift generate a lifetime value from customers greater than the cost of acquiring the customer? For that matter, what is the cost of acquiring and onboarding a customer? How much investment will be required in sales, support, + R&D infrastructure in the future and what will margins look like after that? In software especially, I think the ‘stay-in-business’ expenditure is much higher than you might think, because if a company is not developing rapidly, it’s actually going backwards.
Getswift’s deals so far mostly seem to be struck with customers on a more individual basis, not a whole-of-organisation deal. This may prove more attractive, for example as individual customers (e.g. franchise owners) lack the ability to develop and maintain their own delivery software. This could see GSW maintain higher margins and build some sort of switching costs in, if it becomes essential to the customers’s business. It does however suggest more difficult growth (time consuming to convince 10m individual businesses to sign up with you) and a more fragmented customer base, which could be good or bad. It’s also important to question how much Getswift is giving away to its enablers like NA Williams who is introducing GSW software to its customers. How much does NA Williams get paid and how much % of the value in these future GSW customers does NA Williams capture for itself?
On the other hand, Getswift has also been striking deals with big companies like Yum! Brands and Amazon, and shareholders are about to find out if GSW has pricing power. For example, Yum!’s competitive position depends at least partly on its cost-competitiveness vs McDonalds and so on. If you think that an average takeaway restaurant might have around 8% NPAT margins, that is $4 profit on a $50 order (excluding delivery costs). If 25.5 cents of this goes to Getswift for the delivery, that’s something like a ~4% reduction in pre-tax profit. Amazon’s margins are much lower. It is hard to see Yum or Amazon giving over a huge share of its profits to their delivery software provider. Customers also hate delivery fees so I do not see those making a comeback to cover the cost.
The Facebook of Logistics
It’s difficult to get a grip on all of these questions and that’s why I think so many people are responding harshly to Getswift, at worst suggesting it is a scam. Some of the comments on the company in the market are not helping, for example calling it the ‘Facebook of Logistics’, a ridiculous title as there are not many similarities between the two in my opinion. Facebook provides a highly functional, multipurpose platform which leeches off user activity and has extraordinary network effects and switching costs. Getswift is a discrete, single-purpose piece of software and, as I just said, it is difficult to determine if it has any of those features.
Be that as it may, the company’s been in my too-hard basket until yesterday when the Amazon announcement came out. And I now think Getswift could be about to run headlong into a brick wall. It’s the classic an irresistible force meets an immovable object parable, only in reality there are no irresistibles, and we will see if it’s Amazon or Getswift that gets moved.
Getswift meets Amazon
I have no idea what Getswift’s deal with Amazon is. It’s a ‘Master Services Agreement’ so Getswift provides a service of some sort and in return Amazon (or someone) pays Getswift. Since we are rampantly speculating, I’d say the deal is perhaps offering Getswift software to Amazon 3rd-party resellers in order to let them do their own deliveries if they choose. If I’m right, this may let Getswift retain acceptable margins and $ per delivery, for the reasons I highlighted above (lack of customer ability to develop own solution, possibly hard to switch etc).
Course, maybe Getswift just provides the software for the food truck that sells smoko to Amazon warehouse workers. I wouldn’t get out of bed for a deal like that, but how would you know?
Still, unlike previous deals including the NA Williams deal, a Master Services Agreement (MSA) with Amazon implies a pricing contract as well as limited pricing power for Getswift. Getswift renders a service to Amazon and Amazon decides if it is worthwhile on an ongoing basis (every couple of years, or whatever, but of course the terms of the contract are not disclosed). Getswift would not appear to have much pricing power under this arrangement – just look at Vita Group (ASX: VTG)’s MSA with Telstra (ASX: TLS). Telstra keeps walking back Vita’s remuneration and Vita says ‘thank you sir’.
If however I’m wrong and the deal is with Amazon itself, providing software for last-mile delivery, which is what the market currently seems to think, then I have appropriated a few thoughts from the Twitterati:
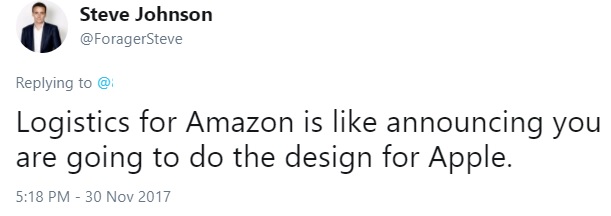
and:
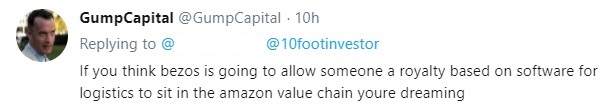
For this kind of deal, in my opinion you can draw a lot of assumptions even without having the first skerrick of information about the contract:
- Getswift needs Amazon a lot more than Amazon needs Getswift.
- Getswift is replaceable. Amazon has logistics expertise, tech expertise, a massive budget, and can build whatever it wants:
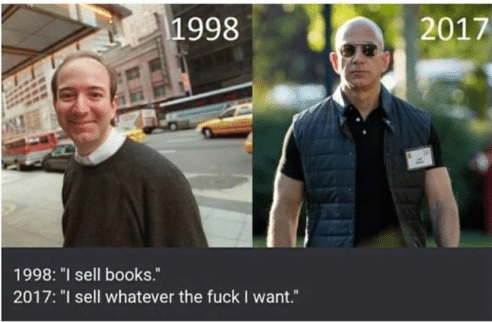
- As a result, Getswift (like all of Amazon’s suppliers) likely has minimal pricing or negotiating power.
- Amazon is ruthless with its suppliers, grinding their margins down to zero. Do you want to sell serious volumes? You need to be on Amazon. Amazon is going to make you pay for the privilege, capturing most of your historical margins for itself.
- Amazon is ruthless with 3rd party operators on its platform. It actively bids its products a few cents cheaper than competitors, for example. If Getswift supplies 3rd party operators with its software via Amazon, it may actually find Amazon competing with it to sell delivery software in the future.
Getswift’s payments per delivery have been around 25.5 cents as of the most recent quarter on a reported revenue basis ($255k revenue, $175k in cash receipts, 1m deliveries). The NA Williams deal implies around 13 cents ($138m revenue divided by ‘over 1bn deliveries’). With Amazon, in my opinion, I would not be surprised to see Getswift getting as little as 5 cents per delivery or less, and that declining over time as Amazon renegotiates. That’s if Amazon is the end customer and not 3rd party resellers.
You do not know which is the case, and neither do I. I quote:
“Due to the terms and conditions of the agreement and the highly sensitive nature, no further information will be provided by the company other than to comply with regulatory requirements for disclosure.”
Highly sensitive for who?
“Due to the terms of the agreement (with Amazon) the number of deliveries this agreement may generate is currently not determinable.”
So ultimately there is a significant degree of uncertainty regarding Getswift’s value and I think it is near enough impossible (for me, at least) to determine the company’s intrinsic value with any accuracy. I could forecast x transactions at this price or that price, but I don’t know how much tech support staff, sales staff, R&D, marketing, and so on will be required to build and maintain Getswift’s position. This is a not a value investment. The only way Getswift actually makes any serious money for investors – And we’re talking about a 10x sales multiple being ‘fair value'(GSW currently priced at ~750x annualised sales) – is if it builds a system from which it can grow rapidly and persistently extract returns well above the cost of capital over the next decade or more.
I labour over this point because it is very easy to forecast revenues to the sky based on the numbers that Getswift has put in its recent presentations. However GSW’s ability to a) deliver on its promises and b) maintain its margins in the face of customers with much greater pricing power are great unknowns.
Getswift needs to suck value out of other players’ pockets, but it does not look like it is currently in a position to do that. I also don’t think the information publicly exists yet that would let an investor determine that unequivocally either way, but the company’s market capitalisation is seemingly already pricing it in.
But hey at least they love their work. Look at how enthusiastic they are to be returning to trade on Monday:

source: LinkedIn
You can’t put a price on passion.
I have no financial interest in any company mentioned (including the US-listed and unlisted ones). This is a disclosure and not a recommendation.